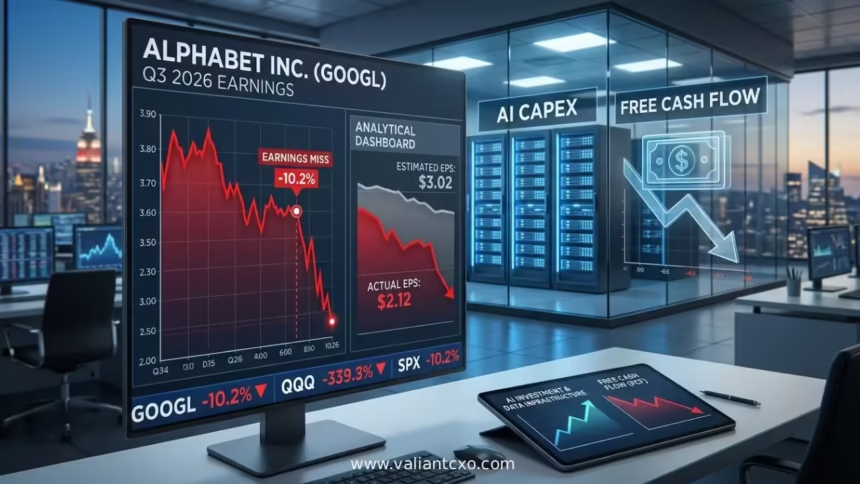
Alphabet Q3 2026 earnings analysis shows a company growing fast at the top line while reported profits took a hit from one large investment mark and heavy AI spending. Revenue climbed 25% to $127.6 billion. Operating income rose 30%. Google Cloud more than doubled. Yet net income fell and the stock posted its worst single-day drop ever.
Here’s the snapshot that matters:
- Revenue hit $127.58 billion, up 25% year-over-year, but slightly missed consensus.
- Reported diluted EPS came in at $2.12 versus roughly $3.02 expected; adjusted EPS was $2.67.
- Google Cloud revenue surged 103% to $30.7 billion with operating margin expanding to 36.2%.
- Search & other revenue grew 12% to $63.4 billion.
- Free cash flow turned negative $9.1 billion after $51.4 billion in capital expenditures.
- An $8.7 billion unrealized equity loss, driven mainly by SpaceX, cut EPS by $0.55.
The numbers tell two stories at once. The core business kept expanding. Accounting noise and infrastructure spending dominated the headlines.
The core operating picture from Alphabet Q3 2026 earnings analysis
Alphabet Q3 2026 earnings analysis Google Services still carried the load. That segment generated $96.3 billion in revenue, up 11%. Search remained the biggest piece at $63.4 billion. YouTube advertising added $11.2 billion. Subscriptions, platforms and devices contributed $14.3 billion.
Google Cloud was the standout. Revenue more than doubled to $30.7 billion. Operating income more than tripled to $11.1 billion. The backlog sat at roughly $561 billion. Cloud now accounts for about 24% of total Alphabet revenue, up from under 15% a year earlier.
CEO Sundar Pichai noted that AI investments drove the highest year-over-year search query growth rate in five years. The Gemini app reached one billion users. First-party model APIs processed nearly 32 billion tokens per minute.
Operating income overall rose 30% to $40.6 billion. Operating margin expanded to 31.8%. Those are healthy numbers by any standard.
Where the reported earnings went sideways
Alphabet Q3 2026 earnings analysis Two items pulled reported profit lower. First, other income and expenses swung to a negative $8.2 billion. CFO Anat Ashkenazi said this was due primarily to an unrealized loss on the SpaceX investment after its share price declined in the quarter. That single mark reduced diluted EPS by $0.55. For the full breakdown of how that investment mark landed and why the stock reacted so sharply, see our detailed look at the [Alphabet SpaceX investment loss stock reaction](Alphabet SpaceX investment loss stock reaction).
Second, capital spending hit $51.4 billion. Operating cash flow was $42.3 billion. The gap produced negative free cash flow of $9.1 billion. Capex guidance for the full year stayed in the $195–$205 billion range, with management signaling further increases in 2027.
A European Commission fine payment also absorbed cash. None of this changed the underlying demand trends, but it changed the reported bottom line and the market’s mood.
Alphabet Q3 2026 earnings analysis: key numbers at a glance
| Metric | Q3 2026 | Year-over-Year Change | Notes |
|---|---|---|---|
| Total Revenue | $127.6 billion | +25% | Slight miss vs consensus |
| Google Cloud Revenue | $30.7 billion | +103% | Margin 36.2% |
| Search & Other Revenue | $63.4 billion | +12% | Solid but slower growth |
| Operating Income | $40.6 billion | +30% | Margin 31.8% |
| Reported Diluted EPS | $2.12 | –26% | Impacted by equity loss |
| Free Cash Flow | –$9.1 billion | Sharp decline | Capex $51.4B |
| Capex | $51.4 billion | +114% | Mostly AI infrastructure |
The table makes the split obvious. Growth engines fired. Reported profit and cash flow felt the weight of investment marks and build-out costs.
Step-by-step action plan for reading these results
- Start with operating income and segment growth. Those numbers show whether the business itself is accelerating or slowing.
- Adjust for the equity securities mark. Treat the SpaceX-related loss as non-operating noise unless the company begins selling the stake.
- Compare free cash flow to the capital expenditure plan. Negative FCF is expected during heavy build years; the question is whether returns follow.
- Watch Cloud backlog and margin trends. A $561 billion backlog and expanding margins signal durable demand.
- Track search growth rates and AI-driven query increases. Pichai highlighted the highest query growth in five years—monitor whether that continues to convert into advertising dollars.
- Note the 2027 capex commentary. Management has been clear that spending will rise further. That shapes the cash-flow outlook for the next several quarters.
Alphabet Q3 2026 earnings analysis In my experience, investors who isolate the operating trajectory from one-time marks and infrastructure spikes make cleaner decisions. What I’d do if evaluating the stock after this print: focus on Cloud’s path to higher contribution margins and whether Search stabilizes in the mid-teens growth range.
Common mistakes in interpreting Alphabet Q3 2026 earnings analysis
Mistake 1: Treating the $2.12 EPS as the true run-rate.
Fix: Strip out the $0.55 equity-loss impact. The adjusted figure sits closer to $2.67 and still reflects solid operations.
Mistake 2: Assuming negative free cash flow signals a broken model.
Fix: Capex is front-loaded for AI capacity. Look at the multi-year plan and the Cloud backlog instead of a single quarter’s FCF.
Mistake 3: Over-weighting the one-day stock drop.
Fix: The roughly 12.6% decline wiped hundreds of billions in market value, but one-day reactions often reverse once the operating details settle in.
Mistake 4: Ignoring the Cloud margin expansion.
Fix: Operating margin in Cloud jumped from 23.7% a year earlier to 36.2%. That improvement matters more than the absolute spending level.
Mistake 5: Missing the query-growth comment.
Fix: Highest search query growth in five years, powered by AI features, is a leading indicator. Watch whether advertising monetization keeps pace.
The bigger strategic read
Alphabet is spending aggressively to stay at the frontier of AI infrastructure and models. Cloud is capturing that demand at scale. Search is adapting with AI Overviews and longer, multimodal queries. The SpaceX mark created noise—see the full [Alphabet SpaceX investment loss stock reaction](Alphabet SpaceX investment loss stock reaction) for how that single position moved reported earnings and the stock—but it does not alter the operating trajectory.
Alphabet Q3 2026 earnings analysis Cash and marketable securities remain substantial. The balance sheet can support the investment cycle. The open questions are timing of returns on the new capacity and the pace at which Search advertising growth re-accelerates.
Key Takeaways
- Alphabet Q3 2026 earnings analysis reveals strong top-line and operating growth alongside a reported-earnings miss driven by an investment mark and elevated capex.
- Google Cloud more than doubled revenue and sharply expanded margins, now contributing nearly a quarter of total sales.
- Search grew 12% with the highest query growth rate in five years, helped by AI features.
- The $8.7 billion equity loss (primarily SpaceX) reduced EPS by $0.55 and amplified the market reaction.
- Free cash flow turned negative $9.1 billion as capital spending hit $51.4 billion.
- Full-year 2026 capex guidance held at $195–$205 billion, with further increases expected in 2027.
- Operating income rose 30% and margins expanded, showing the underlying business remains healthy.
- Investors should separate operating performance from non-cash marks and temporary cash-flow pressure.
Alphabet Q3 2026 earnings analysis Alphabet delivered another quarter of double-digit revenue growth and accelerating Cloud momentum. The reported numbers looked weaker because of accounting marks and the cost of building AI capacity at scale. The next few quarters will show whether that capacity begins converting into higher free cash flow. Watch Cloud margins, search monetization, and the 2027 spending trajectory. Those are the real dials.
FAQs
What stood out most in the Alphabet Q3 2026 earnings analysis?
Google Cloud’s 103% revenue growth and margin expansion to 36.2% were the clearest positives. The $8.7 billion equity loss and negative free cash flow dominated the negative headlines.
Why did reported EPS miss so badly?
An unrealized loss on equity securities, mainly the SpaceX position, reduced diluted EPS by $0.55. Operating results were stronger than the headline number suggests.
Is Alphabet’s free cash flow problem structural?
Not yet. It reflects deliberate front-loading of AI infrastructure. Management has guided for elevated spending into 2027. The test is whether returns follow the capacity build.