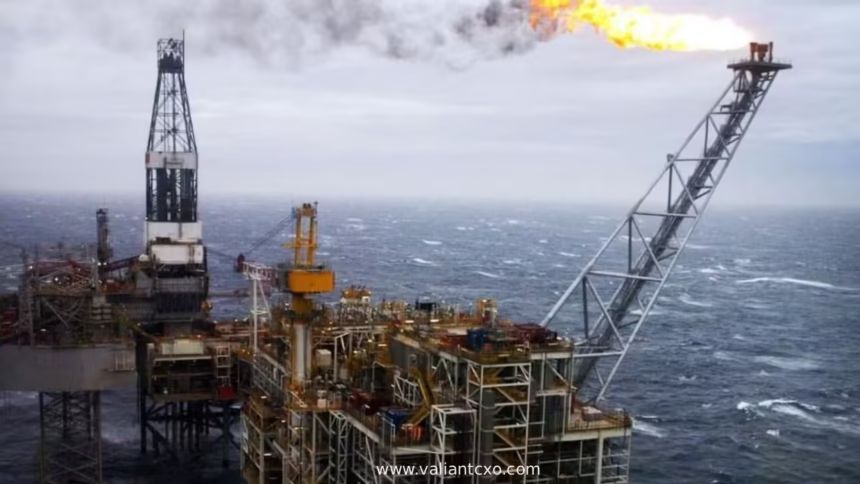
UKCS decommissioning cost trends show a basin spending record sums while the remaining bill refuses to shrink much. Operators poured £2.6 billion into wells, platforms and subsea work in 2025—the highest annual figure yet. Yet the estimated cost to finish the job only edged down to £43.4 billion. Inflation, tight specialist vessels and competition from other energy projects keep offsetting the efficiency gains teams are delivering.
Here’s the snapshot that matters:
- 2025 spend hit a record £2.6 billion, up from £2.4 billion the year before.
- Remaining UKCS decommissioning liability stands at £43.4 billion in 2025 prices.
- Nearly half that total—around £21 billion—is expected to be spent by 2032.
- Well plug and abandonment accounts for roughly half of all forecast costs.
- Operators worked 257 wells in 2025 and took 114 to final abandonment status.
- A new industry charter targeting vessel-based wellhead removal could cut that slice of the bill by about 30 percent, or £200 million.
Those numbers set the stage for the next decade of activity. The window for locking in lower costs is open now. Miss it and the total climbs further.
What the latest UKCS decommissioning cost trends actually reveal
UKCS decommissioning cost trends The North Sea Transition Authority’s August 2026 Cost and Performance Update lays the picture bare. Since the start of 2023, industry has already spent about £7 billion. That outlay should have cut the remaining estimate. Instead, inflation and resource competition pushed the number higher even as actual work accelerated.
Wells dominate the ledger. Platform and subsea well abandonment together make up close to 50 percent of the remaining forecast through 2032. In 2025 alone operators spent roughly £1.3 billion on well work. More than 250 wells saw activity and over 100 reached final abandonment. A backlog of about 500 wells still waits for that final step. Another 1,000-plus wells are scheduled for the next five years. Activity has to ramp hard if the industry is to stay on track and give the supply chain the visibility it needs to keep capacity in the UK.
Platform and topsides removal also rose. So did subsea infrastructure work. The positive signal sits in the contracting numbers: 71 percent of the value of decommissioning contracts awarded in 2025 went to UK-based companies. That exceeds the North Sea Transition Deal targets and keeps skills and vessels on the doorstep rather than drifting overseas.
Operators who have already locked in North Sea oil and gas production efficiency improvements sit in a stronger position. Higher uptime and lower unit costs during the producing years free cash and extend field life just enough to sequence decommissioning more deliberately. The link is direct: the same discipline that cuts losses while the wells flow also cuts the eventual clean-up bill.
Drivers pushing UKCS decommissioning cost trends higher—and the levers that can pull them back
UKCS decommissioning cost trends Three forces keep the total stubborn. First, inflation in vessel day rates and specialist equipment. Second, competition for those same assets from offshore wind, carbon storage and other energy projects. Third, the simple fact that many assets are older and more complex than the early decommissioning campaigns of a decade ago.
The counter-levers are already in play. Collaboration is rising. Operators are sharing vessels, data and lessons more openly. Longer-term contracts give the supply chain confidence to invest in UK capacity. Technology trials—especially for wellhead removal from vessels instead of heavy rigs—are moving from pilot to standard practice. Industry estimates put the potential saving on remaining subsea wellheads at 30 percent, roughly £200 million.
Post-cessation of production running costs also matter. The longer a platform sits idle after last oil, the higher the bill. Teams that plan the transition from production to decommissioning tightly keep those interim costs down.
Step-by-step plan for operators facing rising UKCS decommissioning costs
If I were taking over a portfolio with several assets heading toward cessation of production, this is the sequence I would run.
- Pull the latest internal cost estimate and map it against the NSTA’s £43.4 billion basin total. Identify which assets sit in the top quartile for cost risk.
- Rank every well by complexity, remaining barriers and potential for vessel-based rather than rig-based abandonment. Prioritise the easiest 30 percent for 2026–27 campaigns.
- Lock multi-year vessel and vessel-of-opportunity contracts now. Spot rates will only get tighter as wind and CCS projects ramp.
- Bundle platform and subsea scopes across operators where geography allows. Shared mobilisation is the single fastest cost cutter.
- Run a full post-CoP cost model for every asset. Set a hard target to keep idle time under 18 months.
- Feed actual performance data into the NSTA benchmarking tools so the whole basin learns faster.
- Sequence the work so that cash freed by ongoing North Sea oil and gas production efficiency improvements funds the early decommissioning campaigns rather than waiting for final field life.
Do those seven steps in order and the portfolio-level bill drops. Skip the ranking exercise and you end up paying premium rates for the hardest wells first.
Common mistakes that inflate UKCS decommissioning costs
UKCS decommissioning cost trends The classic error is treating decommissioning as a future problem while the asset is still producing. Teams that wait until cessation of production to start detailed planning almost always face higher vessel rates and longer schedules. Fix: begin the decommissioning execution plan at least three years before last oil.
Second mistake: over-specifying every well to the same heavy-rig standard. Many subsea wellheads can be removed safely from a vessel at a fraction of the cost. Fix: adopt the new industry charter approach and challenge every well for the lightest competent method.
Third: fragmented contracting. Awarding small packages year by year leaves the supply chain unable to invest and keeps day rates high. Fix: move to multi-year, multi-operator frameworks wherever possible.
Fourth: ignoring the learning curve already visible in the NSTA benchmarking data. Operators still in the third and fourth cost quartiles are leaving money on the table. Fix: use the interactive benchmarking report every quarter and set explicit first-quartile targets.
Cost and activity comparison table
| Metric | 2024 | 2025 | Remaining forecast (2026+) | Notes |
|---|---|---|---|---|
| Annual decommissioning spend | £2.4 bn | £2.6 bn | Avg ~£3 bn/year to 2032 | Record high in 2025 |
| Remaining total cost estimate | £43.6 bn | £43.4 bn | £43.4 bn | Marginal reduction only |
| Wells worked / final abandonment | 238 / 103 | 257 / 114 | >1,000 wells next 5 years | Backlog of ~500 still open |
| Share of contracts to UK firms | — | 71% | Target to maintain | Exceeds Transition Deal goals |
| Potential vessel-based wellhead saving | — | — | ~£200 m (30%) | Based on industry estimates |
UKCS decommissioning cost trends The table makes the pressure clear. Spend is rising, the remaining bill is barely moving, and the well backlog still needs aggressive action.
Key Takeaways
- UKCS decommissioning spend reached a record £2.6 billion in 2025.
- The remaining cost estimate sits at £43.4 billion, with nearly half due by 2032.
- Wells remain the single largest cost component and the biggest opportunity for reduction.
- Vessel-based wellhead removal could save around £200 million on the remaining subsea scope.
- 71 percent of 2025 contract value stayed with UK companies—an important capability signal.
- Operators who improve production efficiency first create more cash and more schedule flexibility for the end-of-life phase.
- Collaboration, longer contracts and early planning are the practical levers that still move the needle.
- The next six years decide whether the UK decommissioning sector stays competitive or loses capacity to other energy projects.
The operators who treat UKCS decommissioning cost trends as an active management problem rather than a distant liability will protect more value for shareholders and taxpayers alike. Start by ranking every well in the portfolio this quarter and testing the vessel-based option on the simplest candidates. That single move sets the trajectory for the rest of the decade.
FAQs
What is the current total remaining cost for UKCS decommissioning?
The North Sea Transition Authority’s 2026 update puts the remaining programme at £43.4 billion in 2025 prices after a record £2.6 billion was spent in 2025.
Why have UKCS decommissioning costs not fallen faster despite higher activity?
Inflation, competition for specialist vessels from wind and carbon-storage projects, and the complexity of older assets have offset efficiency gains delivered by operators and the supply chain.
How do North Sea oil and gas production efficiency improvements affect decommissioning costs?
Higher production efficiency extends field life and generates free cash flow that can be used to fund earlier, better-planned decommissioning campaigns, reducing both idle-time costs and the risk of paying peak vessel rates later.