Triple lock state pension explained – the simple system that decides how much your State Pension rises every April, and why it matters more than ever right now.
Here’s the short version:
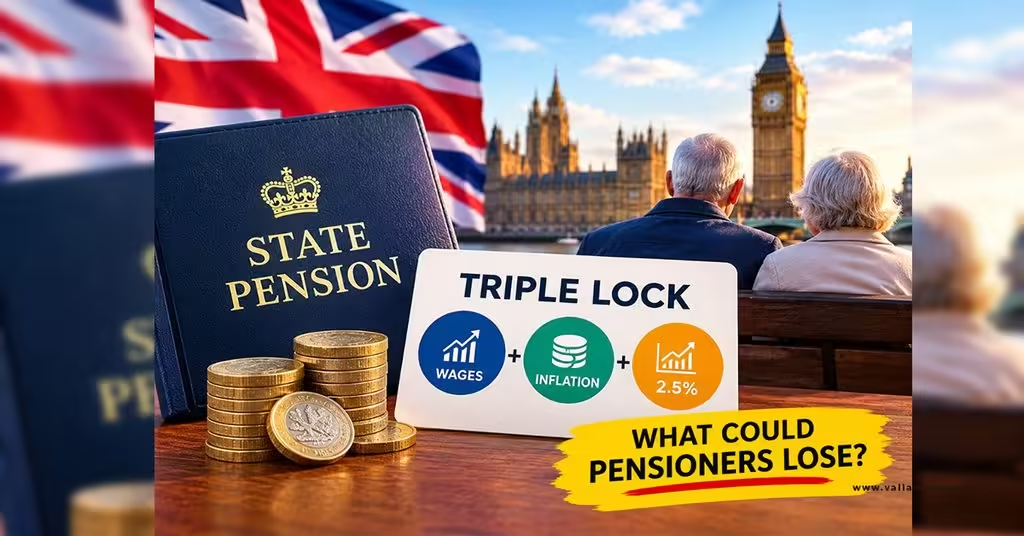
- The triple lock raises the basic and full new State Pension by the highest of three figures: September CPI inflation, average earnings growth (May–July), or 2.5%.
- For April 2027 the earnings figure of 3.9% wins, taking the full new rate to around £250.70 a week (£13,036 a year).
- That rise is exactly why will the state pension exceed the personal allowance in 2027 becomes a live issue for the first time.
- The current formula stays until April 2030; after that the government plans to adjust the earnings link while keeping inflation and the 2.5% floor.
- It only applies to the flat-rate parts of the State Pension – not additional pensions such as SERPS or protected payments.
The triple lock has quietly done more for pensioner incomes than almost any other policy of the last 15 years. Here’s how it actually works, what the numbers look like for 2027, and what changes are coming.
How the triple lock state pension explained really operates
Every autumn the government looks at three official numbers and picks the biggest one. That percentage is applied from the following 6 April.
- CPI inflation – the September figure published by the ONS in mid-October.
- Average earnings growth – total pay including bonuses for the three months May to July, also from the ONS.
- 2.5% – the statutory floor that stops the pension falling in real terms even if both inflation and wages are weak.
Whichever is highest becomes the uprating. That’s it. No ministerial discretion once the data lands. The same percentage is applied to both the full new State Pension (for people who reached State Pension age on or after 6 April 2016) and the basic State Pension (for those who reached age before that date).
Additional State Pension elements – SERPS, S2P, protected payments – rise only with CPI. The triple lock is reserved for the flat-rate core.
Recent and expected rises under the triple lock
| Tax year | Uprating measure | Full new State Pension weekly | Full new annual (approx) | Basic State Pension weekly |
|---|---|---|---|---|
| 2025/26 | 4.1% (earnings) | £230.25 | £11,973 | £176.45 |
| 2026/27 | 4.8% (earnings) | £241.30 | £12,548 | £184.90 |
| 2027/28 | 3.9% (earnings) | £250.70 | £13,036 | £192.10 |
The 3.9% figure for 2027 is now locked in after September 2026 CPI came in at 3.5%. That single increase is what pushes the full new rate past the frozen £12,570 personal allowance – the precise point covered in detail in our guide on will the state pension exceed the personal allowance in 2027.
Why the triple lock has been so powerful
Since it started in 2011 the mechanism has delivered a ratchet effect. In years when earnings or inflation spike, the pension jumps. In quieter years the 2.5% floor still lifts it. Over time the State Pension has grown faster than either prices or wages alone would have allowed. The full new rate is now at a post-war high relative to average earnings.
That generosity is also why the government has decided to adjust it. From April 2030 the pure earnings link will be replaced by a smoother rule that still protects against inflation, keeps the 2.5% floor, and ensures the pension holds its value relative to earnings over the longer term (likely never falling below around 30% of average earnings). The current formula remains fully in force through the rest of this parliament.
Practical impact for your wallet
The triple lock does two jobs at once. It protects the purchasing power of the State Pension when prices rise, and it shares in wage growth when the economy is expanding. For someone on the full new rate the April 2027 rise is worth almost £490 extra a year before any tax.
That same rise is also the reason the tax threshold question becomes real. Once the full new State Pension sits above the personal allowance, pure State-Pension-only households stay protected by the government’s administrative carve-out, but anyone with other taxable income will start to feel the interaction. Understanding the triple lock is therefore the first step to understanding your own tax position next year.
Step-by-step: what you should do with this knowledge
- Check your own State Pension forecast on GOV.UK so you know whether you are on the full new rate, a reduced new rate, or the basic rate.
- Note the expected weekly and annual figures for April 2027 shown above.
- Add any other taxable income you expect (private pensions, savings interest, part-time work).
- Compare the total against the still-frozen £12,570 personal allowance.
- If the State Pension alone will clear the allowance, read the detailed tax rules and reliefs in will the state pension exceed the personal allowance in 2027.
- Diary the Autumn Budget date – that is when the final uprating percentage is formally confirmed and any further detail on the 2030 changes usually appears.
Common mistakes people make about the triple lock
Treating the 2.5% as a guarantee of real-terms growth. It is only a floor; when inflation is higher the pension can still lose purchasing power in the short term.
Assuming every part of your State Pension rises by the full triple-lock percentage. Additional pensions do not.
Thinking the 2030 change starts next year. It does not – the current rules run until April 2030.
Ignoring the interaction with the personal allowance freeze. The triple lock keeps lifting the pension while the tax threshold stays still; that is the source of the 2027 crossover.
Key Takeaways
- The triple lock is simply the highest of CPI, earnings growth or 2.5% applied each April.
- For 2027 the 3.9% earnings figure wins and lifts the full new State Pension to roughly £13,036.
- That rise is what creates the personal-allowance crossover explained in will the state pension exceed the personal allowance in 2027.
- The current formula is safe until April 2030; after that an adjusted version keeps inflation protection and the 2.5% floor while smoothing the earnings link.
- Only the flat-rate basic and new State Pensions receive the full triple lock.
- Your personal numbers matter more than the headline rate – check your forecast and total income now.
- The Budget will confirm the exact 2027 percentage and may add further detail on the longer-term reform.
The triple lock has been one of the most reliable pieces of retirement policy for more than a decade. Knowing exactly how it is calculated, what it will deliver next April, and how it interacts with the tax system puts you in control. Start with your own forecast, then use the linked tax guide to see whether the 2027 rise changes anything for your household. That is the practical next step.
FAQs
Is the triple lock state pension explained the same for the basic and new rates?
Yes. Both receive the identical percentage uplift each year under the current rules.
Will the planned 2030 changes affect the April 2027 rise?
No. The existing triple lock remains fully in place until April 2030.
Does the triple lock mean will the state pension exceed the personal allowance in 2027 is inevitable?
For the full new rate, yes – the 3.9% rise takes it clearly above the frozen £12,570 allowance. The detailed tax consequences and any reliefs are covered in the linked article.