Lloyds share price forecast 2026 sits at the centre of what many UK retail and income investors are watching right now. The stock trades near 104–106p in mid-October 2026 after a solid 23% rise over the past year, yet it remains well below several analyst targets.
- Analyst median 12-month targets cluster around 121–126p, implying roughly 15–20% upside from current levels.
- High estimates reach 133–140p; lows sit near 93p.
- Strong first-half 2026 results and ongoing capital returns (dividends plus buybacks) underpin the constructive view.
- Key risks include UK economic softness, interest-rate paths, and any Budget-related bank tax changes.
- For income seekers, the forecast yield sits in the mid-4% range for 2026 with room to grow.
Here’s the practical picture for anyone sizing up Lloyds Banking Group (LSE: LLOY) for the rest of 2026 and into 2027.
Where the Share Price Stands Today
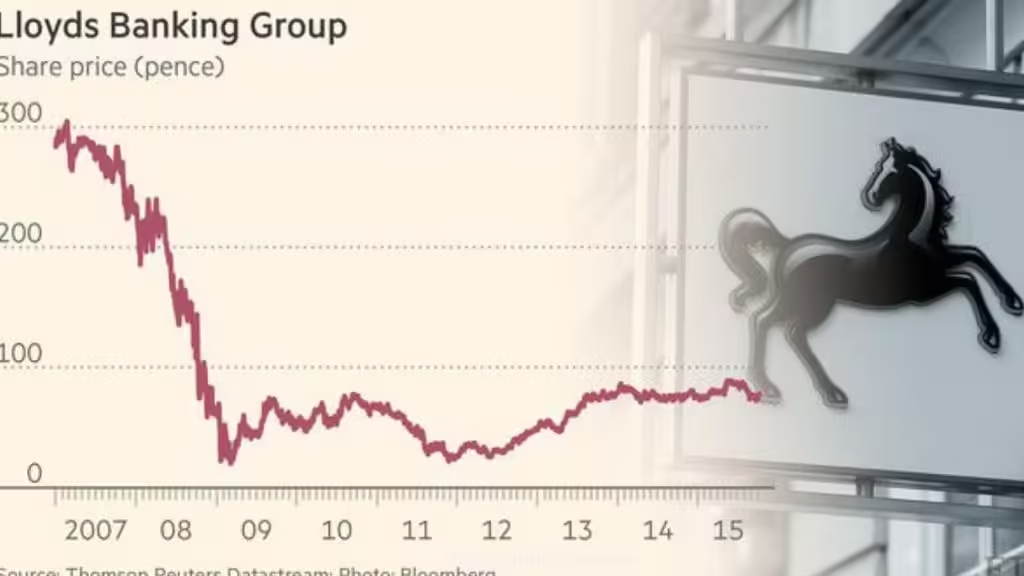
Lloyds closed recently around 105.85p (with intraday moves in the 103–106p zone). That puts it roughly 10–12% below its 2026 high near 118p and well clear of the 52-week low around 82p. One-year performance sits near +23–25%. Market cap hovers around £60–61 billion.
The bank remains a pure-play UK high-street franchise with a dominant deposit base and mortgage book. That domestic focus is both its strength and its vulnerability.
Analyst Views on Lloyds Share Price Forecast 2026
Lloyds share price forecast 2026 Sixteen to nineteen analysts typically cover the name. The median 12-month price target lands near 126p, representing about 19% upside from the recent 105.85p reference. Averages from broader polls sit closer to 121p.
Recent notable calls include:
- Goldman Sachs maintaining a Buy with a 133p target.
- JPMorgan lifting its target to 124p while keeping a Neutral stance.
- Morgan Stanley and others pointing toward the high end of the range (up to 140p).
- A minority of more cautious voices keep targets near or below 100p.
Consensus leans Buy or Outperform, though a handful of Hold and Sell ratings keep the average from looking euphoric. Simply Wall St’s intrinsic-value models also flag the shares as modestly undervalued relative to some estimates.
These numbers are not guarantees. They reflect current earnings power, capital-return plans, and assumptions about the UK rate environment. When rates fall or credit costs rise, the targets move.
What Is Driving the Numbers
First-half 2026 results showed statutory profit after tax of £3.1 billion, up 23% year-on-year. Underlying net interest income guidance for the full year sits above £14.9 billion. Management targets a cost-to-income ratio below 50% and return on tangible equity above 16%. Asset quality remains contained so far.
Capital returns matter. The bank has been running sizeable buybacks (£1.75 billion completed earlier, plus additional programmes) alongside a rising dividend. The interim payout rose 30% and the full-year yield is expected in the mid-4% area, with further growth possible into 2027.
UK GDP expectations and the interest-rate path are the swing factors. A softer landing supports loan growth and lower provisions. Any sharp rise in unemployment or a surprise hike in bank taxes would pressure the multiple.
Step-by-Step Action Plan for Beginners
Lloyds share price forecast 2026 If you’re new to UK bank stocks and thinking about Lloyds, treat it like a long-term income compounder rather than a short-term trade.
- Confirm your time horizon. This is not a stock you buy for a three-month pop. Twelve to thirty-six months is more realistic.
- Check the current dividend and buyback yield. Add them to the capital-gain potential to get a total-return picture.
- Review the latest results and guidance on the company’s investor site. Focus on net interest income, impairment charges, and capital ratios.
- Size the position. Start small—1–3% of a diversified portfolio—because UK banks move with domestic news.
- Decide entry method. Pound-cost averaging over a few months reduces the risk of buying the exact top of a short-term bounce.
- Set a simple monitoring routine: quarterly results, Bank of England rate decisions, and the Autumn Budget.
- Have an exit or rebalance rule. If the thesis changes (sustained rise in bad debts, major regulatory hit), cut the position rather than average down indefinitely.
In my experience, the investors who do best with names like this treat the dividend as the primary return and any share-price appreciation as a bonus.
Common Mistakes & How to Fix Them
Chasing the yield without checking coverage. High yields can signal risk. Fix: look at the payout ratio and free-cash-flow generation relative to the dividend plus buybacks.
Ignoring the domestic UK concentration. Lloyds lives and dies with the UK consumer and housing market. Fix: pair it with more global banks or broader equity exposure if your portfolio is already UK-heavy.
Treating analyst targets as price floors. Targets move when the data moves. Fix: use the range (low–median–high) rather than a single number and update your view after every results release.
Buying only on a dip without a plan. Shares can stay “cheap” longer than expected. Fix: decide in advance what fundamental deterioration would make you sell, then stick to it.
Overlooking currency if you’re a US-based investor. The ADR (LYG) tracks the London price but adds FX noise. Fix: decide whether you want sterling exposure or prefer the ADR for simplicity.
Key Factors That Could Move the Lloyds Share Price Forecast 2026
Positive catalysts include better-than-expected net interest income, continued buybacks, and any evidence that UK growth is firmer than feared. Negative ones centre on rising impairments, a tougher Budget tax package, or a sharper rate-cut cycle that compresses margins faster than cost cuts can offset.
Valuation remains reasonable on a forward P/E basis in the low double digits. That leaves room for multiple expansion if earnings delivery stays clean, but it also means the stock is not priced for perfection.
Key Takeaways
- Current price sits near 104–106p with analyst median targets around 121–126p.
- First-half 2026 results and capital-return programmes support the constructive case.
- Dividend yield in the mid-4% range plus buybacks form a meaningful total-return package.
- UK economic and rate risks remain the main swing factors.
- Position sizing and a clear monitoring process matter more than perfect entry timing.
- Treat the stock as a long-term income holding rather than a speculative trade.
- Always cross-check the latest company guidance and official results rather than relying solely on secondary forecasts.
The real edge comes from understanding the business, not from guessing the exact year-end print. Lloyds will keep generating cash and returning capital as long as the UK consumer holds up. Watch the results, watch the Bank of England, and size accordingly. That approach has served patient investors better than trying to time every 5p move.
FAQs
What is the current consensus Lloyds share price forecast 2026?
Most analyst polls show a median 12-month target near 126p and an average closer to 121p, with highs reaching 133–140p.
Is Lloyds still attractive for income investors in 2026?
Yes for those comfortable with UK bank risk. The combination of a mid-4% yield and ongoing buybacks creates a solid total-return profile if earnings hold.
How sensitive is the Lloyds share price forecast 2026 to interest rates?
Highly. Net interest income is the biggest earnings driver. Faster or deeper rate cuts than expected would pressure the forecast more than most other variables.